Putting Current Bond Yields into Historical Perspective
By Mickey D. Levy
My key observation about the current angst about “high” bond yields: I much prefer high real interest rates associated with healthy economic growth and high returns to capital than low real interest rates associated with economic malaise and low expectations.
Also, while I have long argued that the persistently high government budget deficits and rising debt/GDP are a major problem that involve a misallocation of national resources and must be addressed, I’m not so sure that the recent rise in rates can be attributable to the government’s rising debt.
It’s a tossup between what was more illogical last week, the headlines lamenting “soaring bond yields” or U.S. Secretary of the Treasury Scott Bessent’s announcement that the Treasury had upped its bond buyback program with the hope of lowering yields on long-duration Treasury securities.
A bit of historical perspective is instructive. Current yields are not “soaring” or even “high”—they are in a range that is consistent with current economic and inflation conditions—and these levels are preferable to the low bond yields that characterized the troubled post-Great Financial Crisis period. And Bessent’s Wall Street career in fixed income presumably taught him that interventions aimed at manipulating the bond market would not work; clearly, his announced intervention was a political ploy to placate President Trump. It didn’t work. I strongly recommend Stanley Druckenmiller’s Wall Street Journal article “Let the Bond Market Speak”, August 25, 2026.
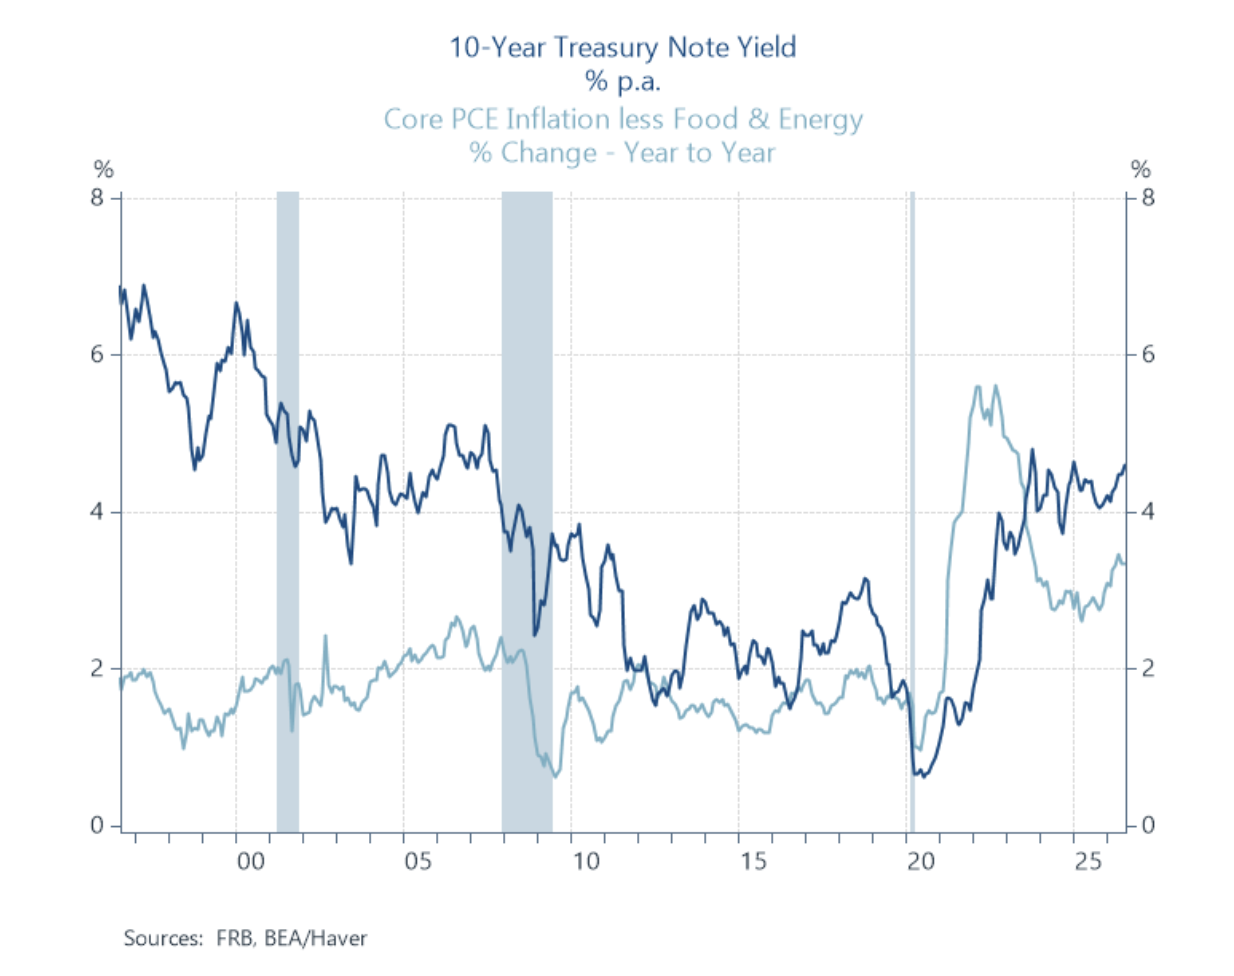
Currently, 10-year US Treasury yields are roughly 4.7%, up from 4.2% earlier in 2026. With inflationary expectations around 2.25%, real rates are in the 2.4%-2.5% range. It’s likely that real rates would be even higher if not for the Trump Administration’s tariffs, clampdown on immigration and other policies that have dampened real growth and threatened longer-run potential. Current real rates are above the low bond yields during 2010-2014 (they ranged between 2.5%-3.25%) that were associated with the disappointingly soft economic recovery from the Great Financial Crisis, lingering high unemployment and diminished expectations, the Fed’s zero interest rates and extended asset purchases and worries that inflation was too low, but significantly below the bond yields of the 1990s and modestly below those that prevailed during portions of the early 2000s.
A cursory comparison of recent decades suggests clearly that the post-GFC period was aberrant period. (Federal Reserve Bank of New York research “Measuring the Natural Rate of Interest”, 2026, estimates that the 2009-2014 period was the low point of the natural rate in modern history.) Yet many financial market participants and commentators use the low rates of that aberrant period as the benchmark for characterizing current yields as high and rising, when economic conditions are far different.
Chart 1 shows 10-year Treasury bond yields and core PCE inflation since 1990. Chart 2 shows the inflation-adjusted bond yields (a measure of inflationary expectations is not available back to 1990) and their correlation to productivity gains.
Chart 1. 10-Yr Treasury Yield and Core PCE inflation
Chart 2. Productivity and 10-Yr Treasury Yields
Bond yields were modestly higher in the early 2000s than currently, particularly in real terms, reflecting the economic growth of the period. Obviously, the debt-financed housing bubble and excesses in the MBS market were part of a misallocation of capital that precipitated the GFC.
The most instructive comparison is between current conditions and the 1990s. Bond yields in the 1990s were much higher than currently, in real and nominal terms, associated with solid productivity-driven economic growth, high returns to capital and high expectations. 10-yr Treasury yields hovered between 6.5%-7% during 1994-1997 and averaged 5.4% in 1998-1999, while inflation-adjusted yields were above 4% for most of the period.
The economic and financial highlights of the 1990s included strong growth and rising wealth (the stock market and housing appreciated faster than the economy); the Fed’s highly successful mid-expansion cycle tightening (February 1994-February 1995) that lowered inflationary expectations and resulted in a soft economic landing; Alan Greenspan’s pushback on tightening monetary policy in response to the strong growth and declining unemployment because he believed the productivity boom would lift real growth and constrain inflation; and strength in capital markets and subsequent decade-end surge in capital markets that culminated with the dot.com bubble.
As a side note, one big difference between the dot.com driven stock market of the late 1990s and the stock market of the 2020s is the dramatic speed of the implementation of AI into commerce and society and the magnitude of the revenues and profits of the AI industry, compared to the lack of revenues and profits of a majority of the dot.com firms of the 1990s.
A second side note contrasts the U.S. government budget in the 1990s to the current situation of worrisome budget deficits and rising debt, with some irony. In the 1990s, budget deficits shrank and toward decade-end, there were budget surpluses that shrank government debt outstanding. This trend reflected sizable declines in defense spending related to the “peace dividend” associated with the end of the cold war combined with the surge in tax revenues related to capital gains taxes generated by the strong stock market.
Fed Chair Greenspan subsequently testified to Congress that declines in government debt were potentially harmful to the US Treasury market and financial markets, and recommended tax cuts (“Outlook for the federal budget and implications for fiscal policy”, Committee on the Budget, U.S. Senate, January 25, 2001). However, while the government budget imbalance was improving in cash flow terms, it was deteriorating on an accrual basis, and longer-run projections of future deficits and debt were mounting, reflecting the pending retirement of the post-war baby boom generation.
Policymakers of the 1990s failed to address these issues, and those demographics now dominate the current budget and projections of the future. The shrinking government debt/GDP ratio in the 1990s played little role in the financial market debate about bond yields, whereas in the current environment even small moves in yields draw attention to the extraordinarily high and worrisome budget deficits and debt.
While I have long argued that the persistently high government budget deficits and rising debt/GDP are a major problem that involve a misallocation of national resources and must be addressed, I’m not so sure that the recent rise in rates can be attributable to the government’s rising debt.
The bottom line is today’s real Treasury bond yields largely reflect the healthy economy and high expected returns on capital, despite erratic policies that constrain growth (Of course, other factors are at play; currently, as shown in Chart 3, high oil prices are clearly influencing bond yields.)
Chart 3. 21-day Change in WTI Oil Prices and 10-Yr Treasury Yield
That doesn’t mean that every investment in AI will provide a healthy return or that the economy will not hit speed bumps along the way. (Nor can the weak housing activity be blamed on “high” mortgage rates; that is attributable primarily to the 50% surge in home values in the early-2020s that the Fed contributed to). But it does reflect the historical perspective that interest rates tend to reflect the economic and inflation conditions of the day. I would prefer even higher real rates and a stronger real US dollar that would stem from reasonable and predictable pro-growth economic policies.
Dr. Levy is Visiting Fellow at the Hoover Institution at Stanford University and member of the Shadow Open Market Committee

Is the U.S. Economy Fragile or Resilient? And a Note on Aggregate Demand and Inflation
Last week the U.S. Department of Commerce announced that real GDP grew at a 1.5% annualized pace in 2026Q1. The media reports and commentary emphasized the weakness of the GDP Report: “U.S. Economic Growth Slows” and “Slow growth highlights economy’s fragile state." Indeed, growth of 1.5% is below standard estimates of sustainable potential growth. But a closer look at the composition of the GDP report and the circumstances suggests that “resilience” and “strength” are better characterizations of the economy than “fragile” or “weak."
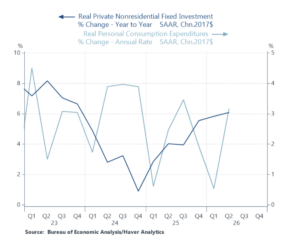
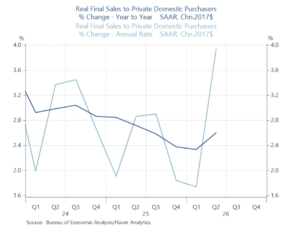
The composition of the 1.5% suggests strength in the domestic economy. Real consumption rose at a 3.2% annualized pace, contributing 2.1 percentage points to real GDP growth, and business fixed investment rose 8.4%, contributing 1.1ppt (Chart 1). Businesses liquidated inventories at a faster pace than Q1, which subtracted 0.7% from domestic production, while the trade deficit widened by $73 billion, reflecting healthy 4.5% growth in exports and an 11.5% rise in imports, which subtracted 1.0 ppt from real GDP. Residential investment, by far the weakest sector of the economy, rose modestly following five consecutive quarters of decline. Adding it up, inflation-adjusted aggregate demand was strong: final sales to domestic private purchasers rose 3.9% annualized, and final sales to domestic purchasers that includes the decline in government purchases rose 3.1% (Chart 2).
Chart 1. Real Business Fixed Investment and Personal Consumption
The context for evaluating the GDP report is important: economy has been hit by a series of supply shocks, including President Trump’s wrong-headed tariffs (and his erratic on-again, off-again implementation of them that has added uncertainty to conducting business), the clampdown on immigration, the high oil prices stemming from the U.S.-Iran war that have added significantly to inflation and business operating costs, and the positive impulse of the implementation and buildout of AI.
Chart 2. Real Final Sales to Private Domestic Purchasers
The tariffs are a negative shock to both supply and demand, which should reduce both aggregate demand and production. Economists in Spring 2025 argued that inflation would rise a lot and real growth would slow markedly, with some calling for recession. Neither happened. Unquestionably, the tariffs distorted production and supply chains and pushed up business operating costs and consumer prices and were distinctly negative for economic performance. Fortunately, households and businesses substituted away from tariffed goods and services, which mitigated the extent of the negative impacts.
The surge in oil prices operates as a negative supply shock that should reduce aggregate demand and raise the portion of it that is inflation and reduce the portion that is real. That didn’t happen either. Even though prices of gasoline and other energy sources surged with the higher oil prices, pushing up business operating costs and lowering real disposable income, aggregate demand accelerated. Business production and investment remained healthy, and consumers smoothed their real spending by drawing down their rate of personal saving and increasing their current dollar spending. The rate of personal saving (the portion of disposable income that is not spent; this measure does not include additions to the stock of wealth reflecting appreciation of financial and housing assets) has fallen from 5.2% in 2025Q1 to 2.8% in 2026Q2. This may have negative implications, as wealthier households spend more while lower income households are squeezed by the higher prices of gas and energy, but it also reflects the adjustability of the economy.
Businesses have been adjusting efficiently to the positive and negative supply shocks, and have liquidated inventories in every quarter since 2025Q2. Likely, this reflects caution in the face of uncertainties about tariffs and product demand, plus the real costs of financing the inventories. The inventory/sales ratio, both including and excluding motor vehicles, has declined since early 2025. This may reflect difficulties businesses have obtaining the products they need to meet demand, but it also reflects business efficiencies.
Business investment has been strong, obviously driven by the AI buildout, but investment in industrial equipment has risen at a healthy clip. Overall, businesses have benefited from the sustained healthy growth in product demand (despite the negative shocks of tariffs and higher oil prices, nominal GDP growth has accelerated) and technological innovations. This is reflected in reported growth in corporate revenues and profits.
The trade deficit has widened since the imposition of tariffs, contrary to the wish and prognostications of the Trump Administration, as growth in imports have outpaced growth in imports. (In nominal terms, the trade deficit has declined modestly.) The trade deficit widened significantly in 2025Q1 as businesses stocked up on imported inventories in anticipation of the tariffs and then fell in the following quarters. It has resumed rising in recent quarters amid rapid gains in both imports and exports. Without question, the tariffs have distorted imports and exports and harmed overall economic performance.
Chart 3. International Comparison of Real GDP, 2019Q4=100
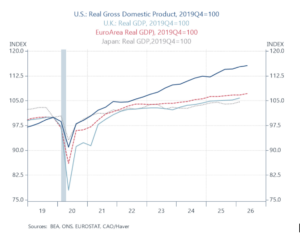
From a global perspective, the U.S. economy continues to outperform. U.S. real GDP growth is higher than every other advanced global economy (Chart 3), and its estimates of the U.S.’s potential growth are higher. Without question, the U.S.’s poor treatment of trading partners is inappropriate and forced changes in the global flows of trade will prove costly, the clampdown on immigration is having a measurable negative impact on labor force growth, and the U.S. faces thorny political-economic issues. Nevertheless, its performance has been resilient, and assessments of the GDP report that say the U.S. economy is fragile and weak are not supported by recent trends.
A note on aggregate demand and inflation. Inflation occurs when aggregate demand persistently exceeds aggregate supply. This demand-supply (im)balance is the macroeconomic environment that determines wage and price setting behavior. (Note that the Fed’s analysis and projections of inflation emphasize wage and price-setting behavior and how it is influenced by labor market tightness and inflationary expectations, while placing little emphasis on aggregate demand relative to productive capacity. This has been the source of its prior errors in judgment and policy.)
The sticky inflation in recent years has been driven by aggregate demand growing too fast (Chart 4). Nominal GDP, the broadest measure of current dollar spending that is a proxy for aggregate demand, doesn’t get much attention; when a GDP Report is released, the near-exclusive focus is on the real figure. That’s an oversight. Nominal GDP rose 7.9% annualized in Q2, lifting its yr/yr rise to 6.5%, up from 6.1% in Q1.
Chart 4. Nominal GDP Growth and PCE Inflation
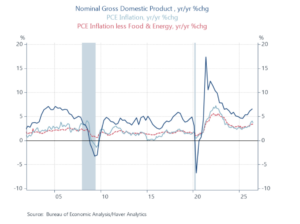
That’s far faster than growth in productive capacity, so it’s not surprising that inflation has remained sticky. (Two notes: 1) the surge in nominal GDP in 2021-2022 was a major contributor to the spike inflation; the Fed ignored the demand side of the equation and instead attributed the inflation to “transitory supply shock”, a glaring miss in economic reasoning and policy, and 2) in 2026Q2, while real GDP rose 1.5% annualized, the GDP deflator rose 6.25%, raising its yr/yr to 4.3%. This is a broader measure of inflation than the PCE Price Index, reflecting inflation in all aspects of GDP. In Q2, while the deflator of final sales to domestic purchasers rose 5.8% in Q2, lifting its yr/yr rise to 4.1%, the deflator of exports rose 25% annualized.)
Higher-than-desired inflation will persist as long as the growth in aggregate demand exceeds productive capacity by so much. The Fed and Congressional Budget Office estimate sustainable potential growth at 2.0%, with roughly 0.5% annual growth in the labor force and 1.5% growth in productivity. I’m more optimistic. But even if sustainable real growth is 2.25%-2.5% reflecting strong productivity gains driven by AI, then aggregate demand is growing too rapidly for inflation to recede. Stated differently, a moderation in aggregate demand is required to lower inflation.
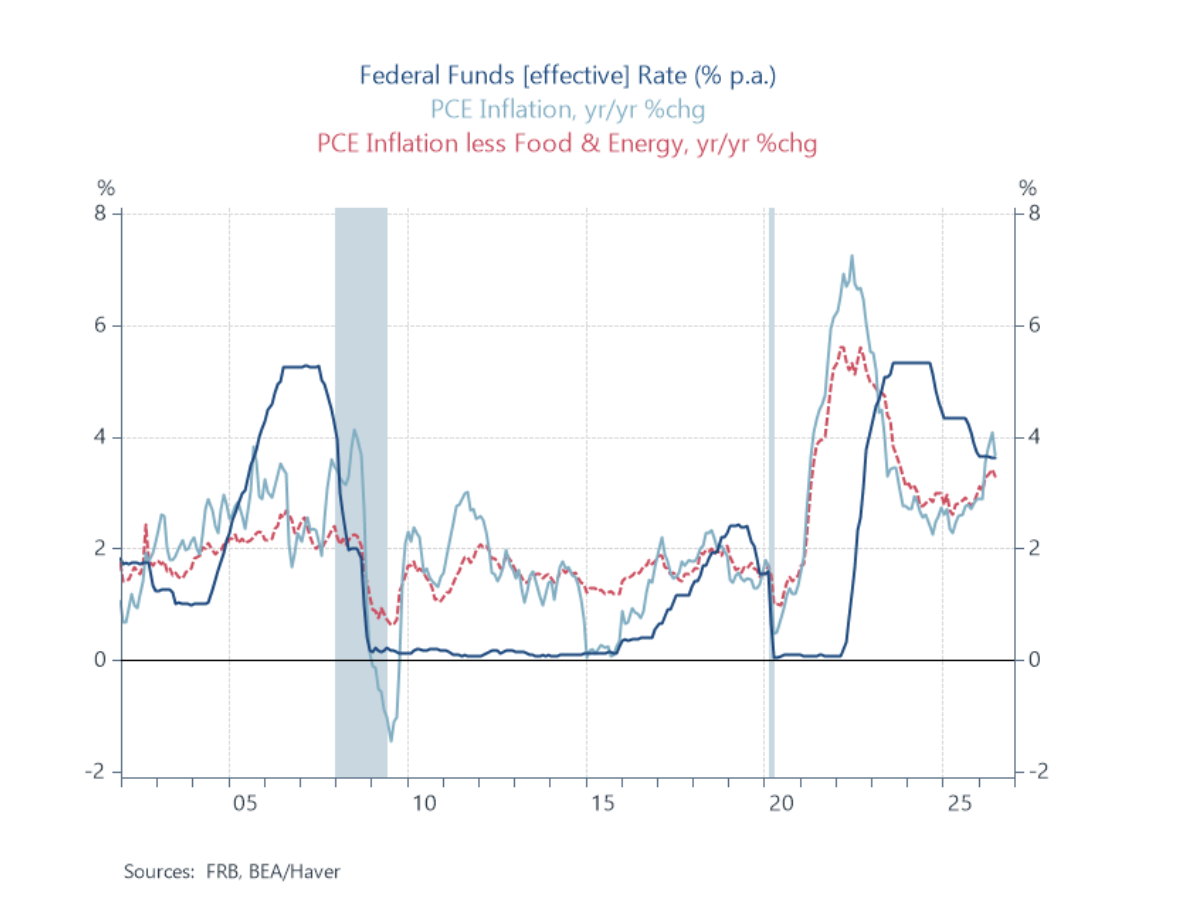
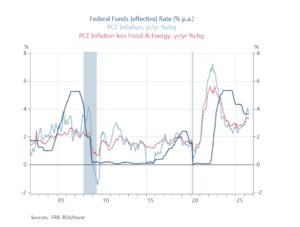
The Fed’s policy is contributing to the fast growth in aggregate demand, along with persistent deficit spending. Several indicators suggest that the Fed’s monetary policy may be too accommodative and generating the stronger growth in demand. The Fed funds rate is below PCE inflation (negative in real terms) and barely above core PCE inflation (Chart 5) (and is below the Fed’s longer-run 1% estimate it perceives would achieve its dual mandate of 2% inflation and maximum employment).
Chart 5. The Fed Funds Rate and PCE Inflation
M2 money supply has picked up to 5.5% yr/yr growth, and money velocity (NGDP/M2) is rising, reflecting the lower demand for money as bond yields drift up (Note: the Fed virtually ignores money supply in its analysis of inflation). The Taylor Rule, a go-to estimate of the appropriate Fed funds rate that would achieve 2% inflation is now above 4% (The Fed does take into account the Taylor Rule, and includes as estimate of it in its Monetary Policy Report to Congress).
All of this suggests that while the Fed voted with three dissents to remain on hold at last week’s FOMC meeting, unless something changes dramatically, it seems likely that the Fed will need to raise rates in the future to slow aggregate demand to eventually achieve its 2% inflation target.
*Dr. Levy is a Visiting Fellow at the Hoover Institution at Stanford University and a member of the Shadow Open Market Committee.